Mark Cuban was recently asked a question about artificial intelligence that doesn’t get nearly enough attention.
Not whether AI works. Not whether it will transform business. Not whether it will eliminate jobs or create new ones.
Can the companies spending staggering amounts of money building AI ever earn enough profit to justify the investment?
Cuban’s answer was succinct:
“They’ll never get it.”
I don’t know if he’s right. But the more interesting question is what would have to happen for him to be wrong.
Making Money Isn’t Enough
If you spend $1 trillion building AI infrastructure and the resulting business eventually earns $200 billion, that sounds like an extraordinary amount of money.
But you’re not $200 billion ahead. You’re still $800 billion short of recovering the trillion dollars you put in.
And simply earning back the original trillion isn’t enough, either. Investors expect a return on their capital—and the larger the investment and the longer it remains tied up, the larger that return needs to be. Otherwise, why take the extraordinary risk of building an entirely new industry? You could put the money into Treasury securities and earn a return while taking dramatically less risk.
That’s the hurdle the AI industry ultimately has to clear. It doesn’t merely need to become profitable. It needs to earn back the trillions invested in building the infrastructure, and then generate enough additional profit to deliver an attractive return on that capital.
When you frame the question that way, the numbers start getting uncomfortable.
The Infrastructure Doesn’t Last Forever
There’s another complication that makes the economics particularly interesting.
Much of this money isn’t being spent on bridges or buildings that might remain useful for 50 years. It’s being spent on some of the fastest-depreciating technology humans manufacture.
GPUs become obsolete.
Servers get replaced.
Networking technology advances.
New chips deliver substantially more computation per watt. New model architectures may require different hardware. Techniques become more efficient.
Cuban made precisely this point. The enormous data-center capacity companies believe they need today may look very different as computing gets faster and cheaper.
But Nobody Can Stop
This is where Cuban made what I thought was his most interesting observation.
If you’re one of the companies competing to build the dominant foundational AI model, you almost have to keep raising money.
Because nobody yet knows what this market will ultimately look like.
Maybe it resembles search, where one company captures an overwhelming share of the economics. Maybe it looks more like streaming, where several large competitors survive. Perhaps different AI systems dominate programming, medicine, research, entertainment and other specialties.
Nobody knows.
But if there’s a chance this becomes a winner-take-most market, you cannot afford to discover that your competitor spent $500 billion building the winning platform while you prudently protected your balance sheet.
So you raise.
Then your competitor raises.
You announce another data center.
They announce five.
You secure another hundred thousand GPUs.
They sign a deal for a million.
At some point, spending becomes evidence that you’re still in the game.
And not spending becomes evidence that you’re losing.
The AI Capital Paradox
That creates a fascinating paradox.
The rational strategy for each individual company may be to keep spending enormous amounts of money. But that doesn’t mean the collective investment is rational.
Imagine five companies each conclude they need to spend hundreds of billions to have a shot at becoming one of three eventual winners.
From the perspective of each company, that investment might make sense. The potential prize is enormous, and refusing to compete virtually guarantees losing it.
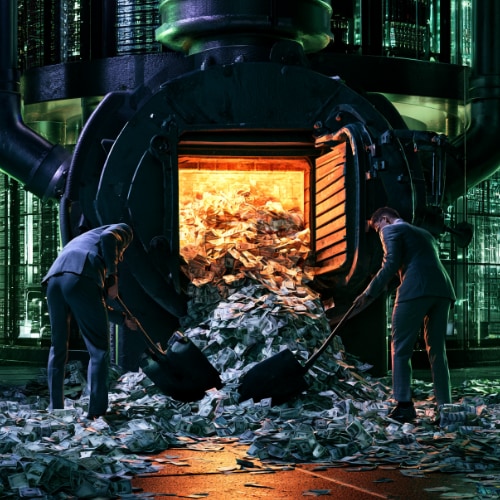
From the perspective of the industry, however, somebody is going to incinerate an astonishing amount of capital.
Perhaps several somebodies.
Cuban put the potential endpoint rather wonderfully. If too many foundational models survive without meaningful differentiation, eventually “you’re just an app.”
Except you spent a trillion dollars becoming one.
AI Can Change Everything and Still Be a Bad Investment
A technology can transform the world without producing adequate returns for the people who financed the transformation.
Warren Buffett famously used airlines as an example. Few technologies changed civilization more profoundly than commercial aviation, yet Buffett spent decades pointing out what a terrible business airlines had historically been for investors. The industry required enormous amounts of capital, suffered repeated bankruptcies, and struggled to produce durable returns. In his 2007 Berkshire Hathaway shareholder letter, he described investors as having poured money into a “bottomless pit.”
His point wasn’t that airplanes were a failure. Quite the opposite. Air travel changed the world. The problem was that changing the world and generating an attractive return on all the capital required to do it turned out to be two very different things.
That’s the distinction worth remembering with AI.
AI could become one of the most consequential technologies of the century. It could transform software, medicine, science, education and entire industries—and Mark Cuban could still be right that investors will never earn an adequate return on the trillions being spent to build it.
Jayson L. Adams is a technology entrepreneur, artist, and the award-winning author of The Quantum Mirror, Ares, and Infernum.
His novels blend high-stakes science fiction, psychological tension, and character-driven suspense. Explore the books at www.jaysonadams.com.